Yes—an investment adviser can help you buy your first Adelaide investment property by turning your goals into a buying brief, assessing properties and coordinating specialist advice where the agreed service includes it. The adviser does not replace your lender, conveyancer or building inspector, and cannot guarantee rental income, capital growth or loan approval.
- An investment advisor can help you buy your first investment property; confirm exactly which buying tasks the engagement includes.
- Axiom Realty offers investment advisory, buyer’s advocacy and property management to South Australian property investors.
- Choose advice around your cash flow, property risks and ownership responsibilities—not a promised return.
- Check representation, referral payments and written deliverables before appointing an adviser.
Can an investment advisor help me buy my first investment property?
Yes. The useful distinction is between advice that helps you decide what to buy and representation that helps you complete the purchase. Ask whether your engagement covers both; the word adviser alone does not establish the service scope.
The investment advisory guide for first-time investors provides further context. Start your 2026 search with a written brief rather than a list of properties: the brief gives every recommendation something concrete to answer to.
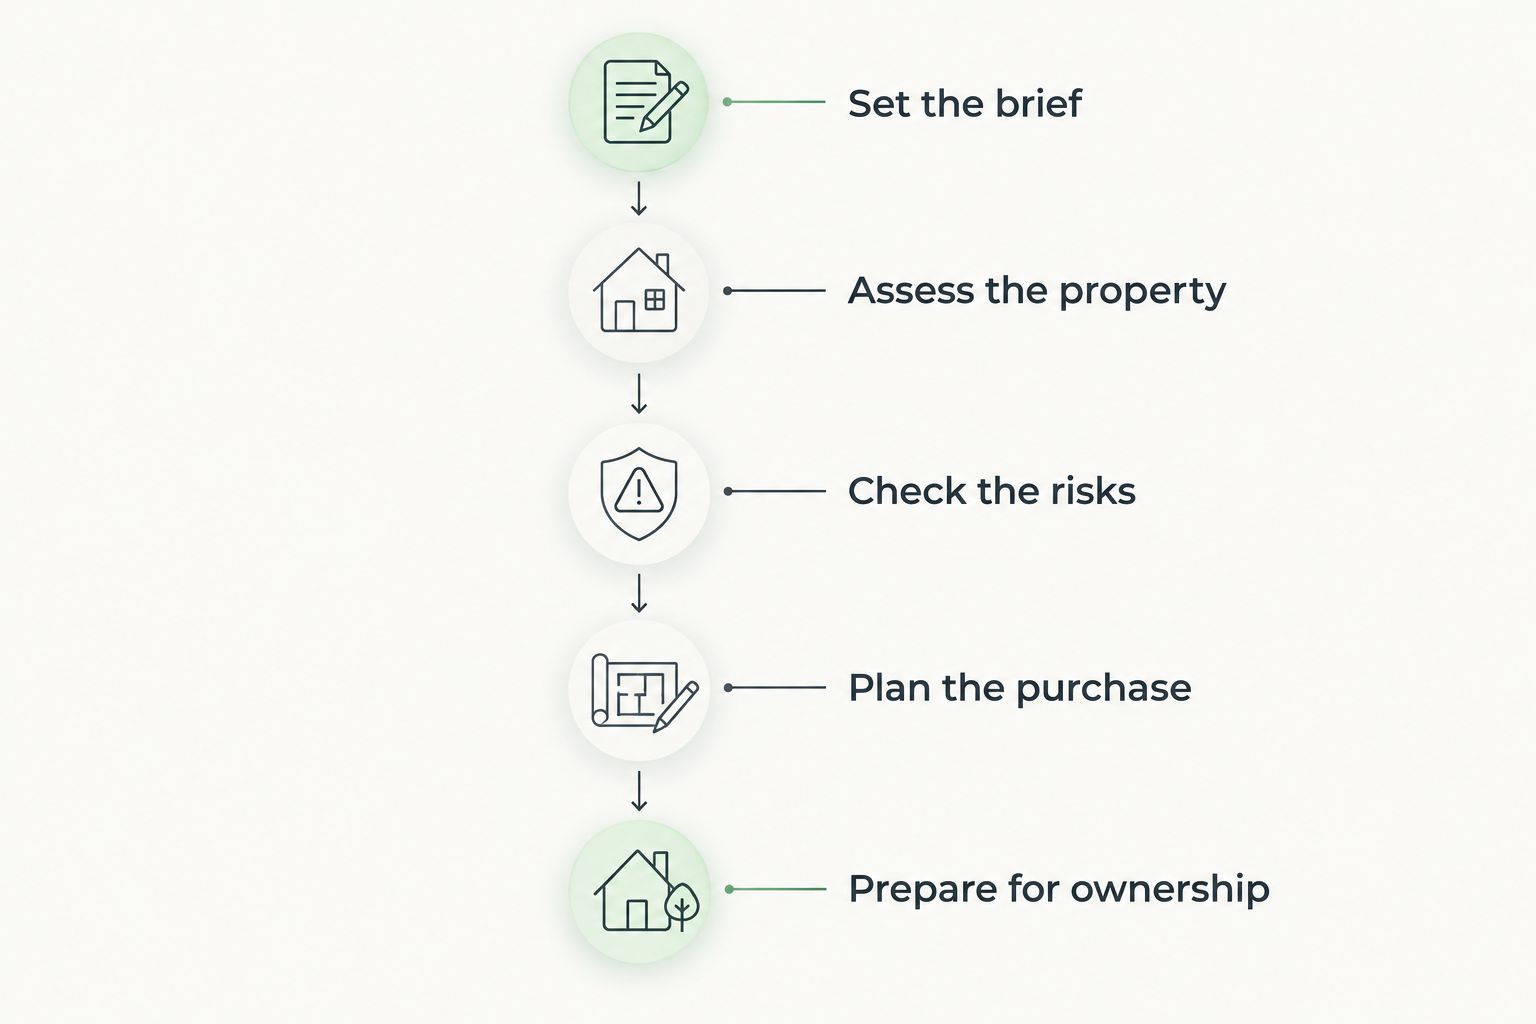
A practical advisory process follows these steps:
- Set the brief. Record your purpose, borrowing position, available cash, ownership plans and limits on ongoing spending.
- Assess the property. Examine comparable sales, rental evidence, condition, ownership costs and restrictions affecting your intended use.
- Check the risks. Separate verified information from estimates and identify the specialists needed to resolve unanswered questions.
- Plan the purchase. Agree who handles inspections, negotiations, contract review, finance and settlement tasks.
- Prepare for ownership. Arrange insurance advice, property management decisions and a maintenance reserve before relying on rental income.
An adviser’s recommendation should explain why a property fits your brief and what would make it unsuitable. A reason to reject a property is as useful as a reason to buy it.
Why this matters before your first Adelaide purchase
A property can satisfy a lender’s requirements without satisfying your investment goals. Borrowing capacity does not tell you whether you can comfortably fund repairs, manage an interruption to rent or hold the property through changing circumstances.
For a first purchase in 2026, ask for a 12-month cash-flow forecast covering the property’s expected income and ownership expenses. Treat it as a planning document, not a prediction: every assumption needs a source or a clear explanation.
Then test a scenario with 1 month without rent, keeping the other assumptions visible. This is a suggested stress test, not an Adelaide vacancy forecast; its purpose is to show whether your cash reserve depends on uninterrupted rent.
Useful advice turns those findings into a decision. If the purchase leaves no room for unexpected spending, change the brief before making an offer.
Which professional should help with which task?
Investment advice, buying representation and loan advice serve different purposes. You can use several professionals, but assign each task explicitly so that an important check does not fall between engagements.
| Professional | Best for | Main contribution | Limit to understand |
|---|---|---|---|
| Property investment adviser | Defining your investment brief | Assesses property choices against your goals and constraints | The agreed scope determines whether buying representation is included |
| Buyer’s agent or advocate | Search and purchase representation | Searches, assesses or negotiates on your behalf within the appointment | Does not replace lending, legal or technical advice |
| Mortgage broker or lender | Assessing finance options | Explains borrowing requirements and the finance application | Finance approval is not an endorsement of investment quality |
| Conveyancer or solicitor | Transaction and contract advice | Reviews legal matters within the engagement | Does not establish the building’s physical condition |
| Building and pest inspector | Investigating physical condition | Reports on the inspection scope and findings | Access restrictions and exclusions limit what the report establishes |
| Property manager | Rental and management planning | Provides rental input and explains management responsibilities | A rental appraisal does not guarantee rent or continuous occupancy |
Choose by the task you need completed, not the title on the business card. Ask every professional to identify what they will deliver and what remains outside their responsibility.
Where an adviser coordinates other specialists, confirm whether you appoint those specialists directly. Coordination is useful, but you still need to understand each engagement and receive the relevant reports.
What should your adviser assess before recommending a property?
A useful recommendation connects the property to your circumstances. A suburb description or attractive listing is not enough to justify a purchase.
Cash flow and reserves
Ask for income and expenses to appear separately, with the assumptions beside them. Loan repayments, insurance, council rates, maintenance, management expenses and relevant shared-property charges belong in the assessment where applicable.
Keep your personal spending commitments separate from the property forecast. A property that appears manageable on paper can still strain your household if your available reserve is overstated.
Rental evidence
Ask what supports the proposed rent: comparable properties, their condition, their location and the relevance of the evidence. An advertised asking rent and a confirmed leasing result are different types of evidence.
For a 2026 assessment, record when the rental evidence was gathered. An estimate needs a date because the circumstances behind it can change before settlement or leasing.
Condition and ownership obligations
A visual inspection does not resolve every maintenance question. Review specialist findings, access limitations and recommended further investigations before treating the property as ready to rent.
For apartments or other properties with shared ownership arrangements, investigate the relevant records and obligations. The purchase involves more than the interior you inspect.
Resale and alternative uses
Ask who the likely future buyer would be and what limits the property’s appeal or intended use. Planning restrictions, unusual layouts and unresolved defects deserve attention before you commit.
An adviser should distinguish an existing, documented use from a proposed improvement. Do not build the investment case around an unverified conversion, subdivision or rental arrangement.
Why the help you need varies
There is no single advisory scope that suits every first-time investor. The right engagement depends on the work your purchase requires and the work you can competently manage yourself.
- Your location: An interstate buyer needs a clear arrangement for inspections, local checks and document handling.
- Your available time: Search support and transaction coordination matter when you cannot manage appointments and follow-ups yourself.
- The property type: A detached house, apartment and proposed development raise different ownership and investigation questions.
- Your financial position: Borrowing limits, existing commitments and accessible reserves shape the buying brief.
- The property’s condition: Defects and incomplete information require specialist investigation, not stronger sales language.
- Your ownership plan: Self-management and professional management allocate different tasks to you after settlement.
Ask the adviser to identify which of these factors changes their proposed work. A broader engagement is useful only when it covers tasks you actually need.
How do you check whether the adviser represents your interests?
Start with a direct question: who is the client in this transaction? Then ask who pays the adviser and whether a seller, developer, referrer or related business benefits from your decision.
A payment arrangement is information you need to evaluate the recommendation. Get it in writing rather than relying on a general statement about independence.
Before signing, request clear answers to these questions:
- Who does the adviser represent for this purchase?
- What services and written deliverables are included?
- Are recommendations limited to particular sellers, developments or referral partners?
- What commissions, referral payments or other benefits must be disclosed?
- Who checks rental assumptions, condition and contract issues?
- What happens if no suitable property meets your brief?
Compare the answers with the appointment documents. If a promised service does not appear in the agreement, resolve the difference before proceeding.
A claim of guaranteed growth or guaranteed investment success is not a substitute for evidence. Keep forecasts separate from contractual commitments and obtain legal advice where a guarantee forms part of the proposal.
What should you do before making an offer?
Before an offer, make sure the purchase decision rests on completed checks rather than an intention to investigate later. Your conveyancer or solicitor should explain the contract implications and the protections appropriate to the transaction.
Use this handover checklist:
- Finance: Confirm your position with the lender or broker, including outstanding requirements.
- Contract: Have the relevant documents reviewed and understand obligations before signing.
- Condition: Read inspection findings, exclusions and recommendations for further investigation.
- Rental plan: Confirm the proposed letting approach, required work and management arrangements.
- Ownership expenses: Update your forecast using property-specific information rather than generic allowances alone.
The building and pest inspection to unconditional offer workflow is a useful companion to this stage. Let your legal adviser determine how inspection findings and unresolved issues affect the contract decision.
For a 2026 purchase, keep the latest documents together and identify which version each professional reviewed. A changed contract, updated report or revised lending condition needs to reach the person responsible for assessing it.
Can an adviser help if you have not chosen an Adelaide suburb?
Yes—an adviser can help turn your requirements into suburb and property criteria. Begin with your financial limits, intended ownership period and management needs rather than asking for a universally best suburb.
Request a side-by-side assessment of 2 shortlisted properties using the same criteria. This is a practical comparison exercise, not a claim that two inspections are sufficient due diligence; consistent criteria help expose trade-offs that separate listing presentations can hide.
Do you still need a conveyancer and building inspection?
Yes—investment advice does not replace legal review or an appropriate building inspection. Each professional answers a different question, so appoint them for the work the purchase requires and read their findings before committing.
Ask your adviser to record unresolved issues alongside the recommendation. A positive overall opinion should not conceal an outstanding contract question or inspection limitation.
Can Axiom Realty help with a first investment purchase?
Axiom Realty offers investment advisory, buyer’s advocacy, property sales and property management to investors and homebuyers across South Australia. Axiom Realty is suited to South Australian investors seeking property investment advisory and buyer’s advocacy.
The relevant advantage is access to services covering purchase advice and ongoing management. The boundary is equally important: confirm which services your engagement includes, who represents you and which independent specialists you need.
Discuss your first investment purchase
Explain your Adelaide buying goals and ask which advisory and buyer’s advocacy services fit your needs.
FAQ
Can an investment advisor help me buy my first investment property?
Yes—an investment adviser can help define your buying brief, assess properties and coordinate the purchase tasks included in the engagement. Confirm whether search, negotiation and transaction support are included rather than assuming they come with advice.
Is an investment adviser the same as a buyer’s agent?
No—the titles do not establish an identical service. Investment advice concerns the purchase strategy and property assessment, while buyer’s representation concerns acting for you during the search or transaction; check the written scope.
Can an adviser guarantee that my Adelaide property will grow in value?
No—an adviser cannot guarantee future capital growth. Ask for the evidence, assumptions and risks behind any forecast rather than treating the forecast as a promised outcome.
Should I speak to a mortgage broker before looking at investment properties?
Yes—establishing your borrowing position helps you set a realistic buying brief. Keep a separate assessment of household cash flow and property expenses because borrowing capacity does not establish investment suitability.
Can I use an adviser if I live outside South Australia?
Yes—an adviser can assist an interstate buyer when the agreed service covers the required local work. Confirm arrangements for inspections, reporting, document review and purchase representation.
What should I ask before appointing a property investment adviser?
Ask who the adviser represents, what they will deliver and how they are paid. Request written disclosure of relevant referral arrangements and identify the legal, finance and inspection work outside the engagement.
Does Axiom Realty offer help beyond investment advice?
Yes—Axiom Realty also offers buyer’s advocacy, property sales and property management across South Australia. Confirm which services apply to your purchase and which require a separate appointment.
One last thing
Ask your adviser to write down the conditions under which they would recommend not buying the shortlisted property. That answer gives you a decision rule before enthusiasm, negotiation or a looming deadline takes over.
For your 2026 purchase, keep that rule beside the buying brief. If new information breaches it, pause and reassess rather than rewriting your goals to fit the property.